The Sunstone Standard | September 2026
Deal Desk
Northeast Alabama Portfolio
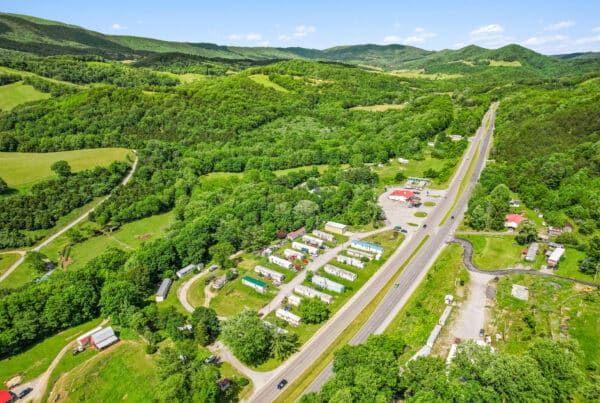
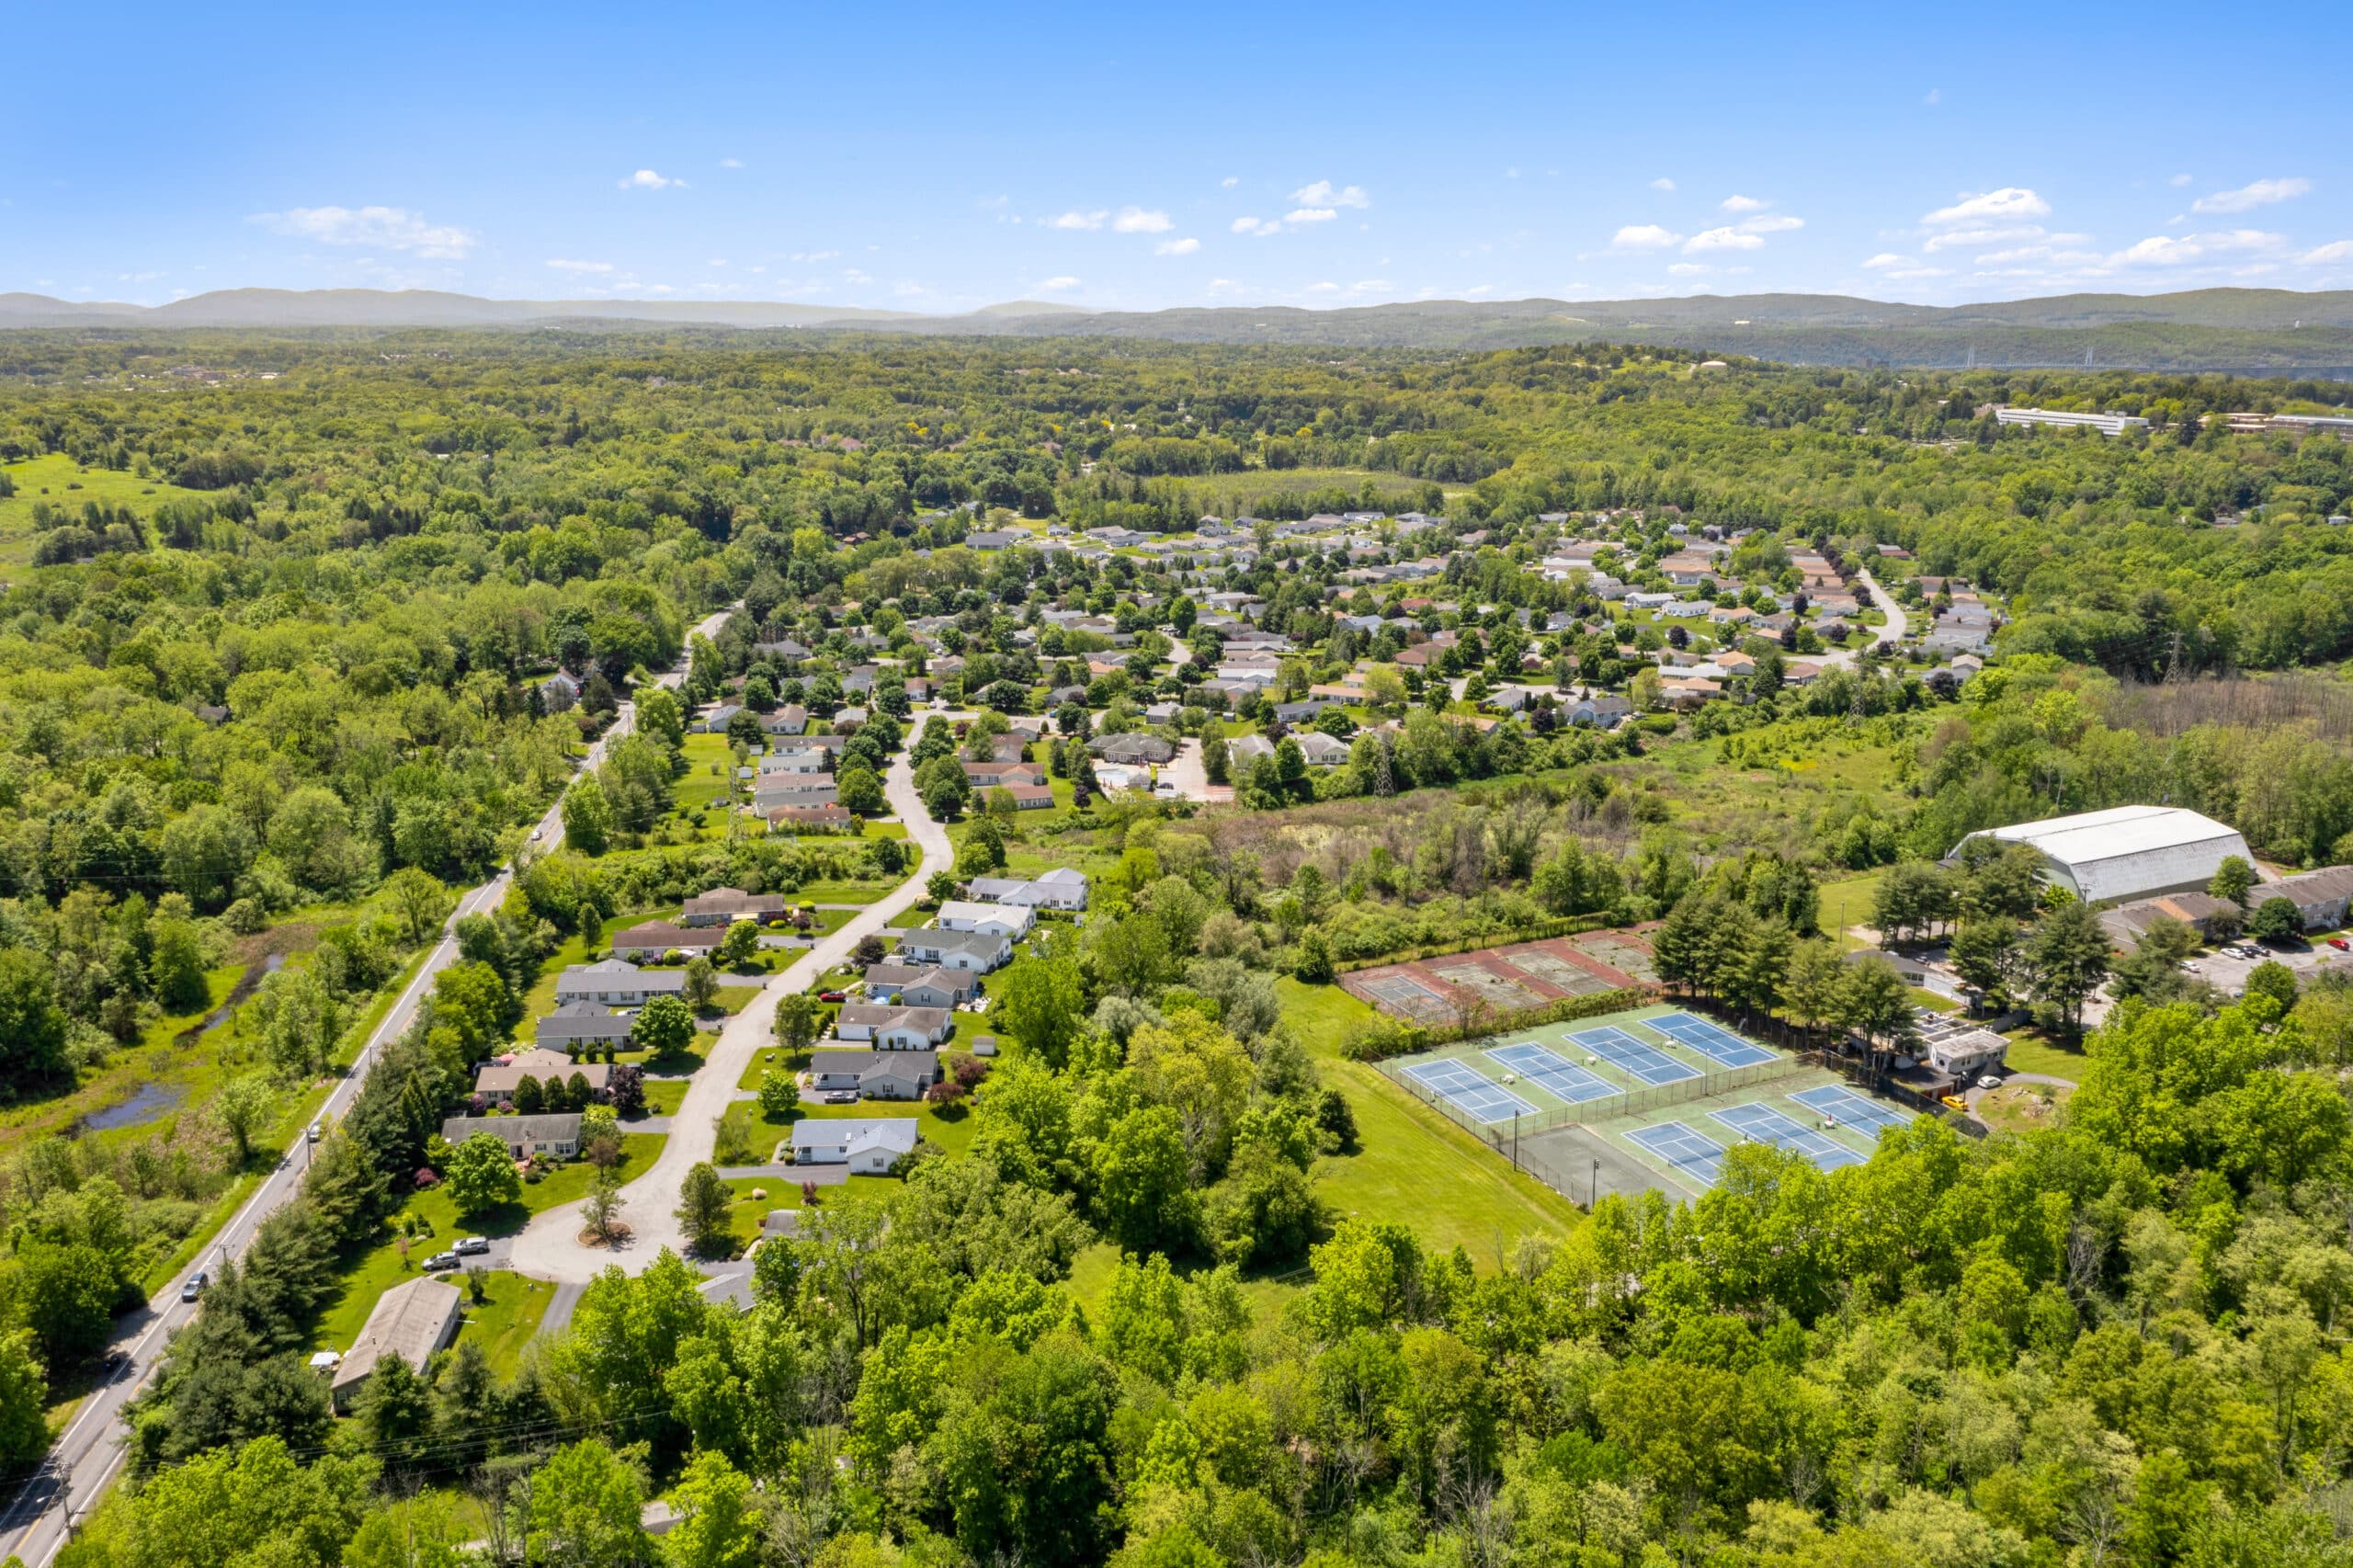
Sunstone exclusively represented the seller in the disposition of a five-community manufactured housing portfolio totaling 283 sites across the Anniston-Oxford-Jacksonville MSA in Northeast Alabama.
The portfolio featured 83% physical occupancy, 49 vacant manufactured home sites, 94 park-owned homes, and average lot rents of $289 per month, along with a diversified mix of tenant-owned homes, park-owned homes, rent-to-own units, and single-family rentals. The combination provided investors with immediate scale and multiple opportunities for future growth through lease-up, infill, home optimization, and strategic rent increases.
Following a targeted and competitive marketing process, Sunstone secured a qualified buyer and guided the transaction through closing.
The sale reflects continued investor interest in communities that combine in-place cash flow with identifiable opportunities to improve performance over time.
For questions about this deal, contact Cesar Ovando (Cesar@SunstoneREA.com) or Enon Winkler (Enon@SunstoneREA.com).
What We’re Hearing
Buyers Are Underwriting the Story Behind the Numbers
Today’s buyers aren’t simply asking what an asset is producing now. They’re looking closely at how credible the path is from today’s performance to tomorrow’s.
Across conversations and transactions, several factors continue to shape that evaluation:
- Infill potential: Is there realistic demand and a practical path to filling vacant sites?
- Rent positioning: How do current rents compare with the market, and where is future growth supportable?
- Home strategy: Can park-owned homes, rent-to-own units, or other inventory be optimized over time?
- Operations: Are expenses, collections, occupancy, and reporting providing a clear picture of performance?
- Market fundamentals: Does local demand support the business plan?
Value-add remains attractive, but buyers are increasingly focused on whether the opportunity is executable, not simply whether it exists.
Capital Minute
Year-End Financing: Why Acting Now Matters for a 2026 Closing
By: Zach Koucos and Chris Collins, Sunstone Capital Advisors
With the fourth quarter rapidly approaching, the window to secure capital and lock in terms for a 2026 closing is beginning to narrow. Lenders are working to hit their annual origination targets, while borrowers are eager to lock in rates, complete acquisitions before tax deadlines, or execute year-end refinances. Processing a loan transaction, whether through Agency programs (Fannie Mae and Freddie Mac), Life Insurance Companies, bridge lenders, CMBS, or regional banks, requires a multi-step execution with strict timing.
Why Timing is Everything Right Now
Waiting even a couple of weeks to move a deal forward can derail a year-end closing target:
- Vendor Capacity: Appraisers, environmental engineers, and survey teams fill their schedules quickly. Late submissions get pushed to the back of the queue.
- Holiday Deadlines: Thanksgiving and the December holiday season compress the final quarter into essentially seven working weeks, creating administrative dead zones.
- Capital Deployment Caps: Lenders with remaining allocation are racing to place capital, but once their capacity or processing bandwidth is maxed out, deals get pushed into Q1.
Taking Control of the Execution
For sponsors and borrowers aiming to close before the ball drops on New Year’s Eve, urgency is the primary strategy. Signing term sheets and moving loans under application immediately ensures priority positioning in lender pipelines, and locks in third-party vendor schedules before the late-season rush hits its peak.
In multifamily lending, the end of the year isn’t December 31st, it’s the moment your application hits the underwriter’s desk. The clock is ticking; getting signed applications in motion today is the single best way to ensure your deal gets across the finish line on time.
For sponsors and borrowers aiming to close before the ball drops on New Year’s Eve, urgency is the primary strategy. Signing term sheets and moving loans under application immediately ensures priority positioning in lender pipelines, and locks in third-party vendor schedules before the late-season rush hits its peak.